One of the biggest determinants of wealth is the way you think about it. Pick up unhealthy ways to see money, and it quickly flees from your pocket: you can see this with compulsive gamblers, as well as get-rich-quick schemers. There are plenty of destructive views regarding wealth, and these are the main ones that affect fresh graduates – learn from the experiences of others, rather than just your own:
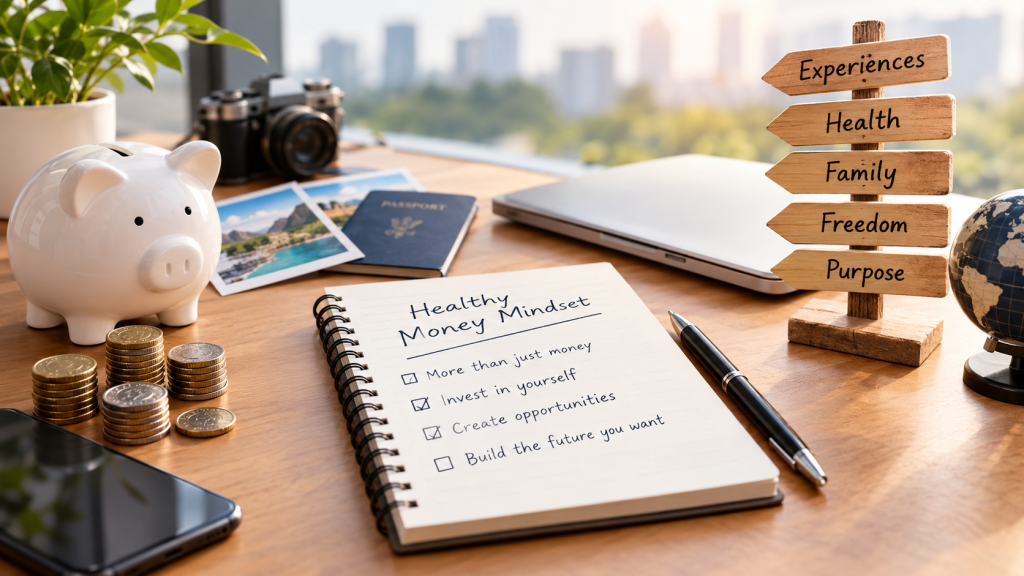
If you think of wealth in purely monetary terms, it can lead to a painful and wasted youth. Here’s why:
If wealth is just money, then being wealthy means having lots of money. The less you spend, the more money you have. The less you explore your world (travel, start new businesses, etc.), express yourself, or live your life, the more money you can hoard and save up.
This may very well lead to you becoming a millionaire many decades down the road; but do you really want to reach your late 60’s as a financially rich person, and realise you’ve suffered all the way? By the time you finally make your million(s), you would have given up on life experiences that can’t be repeated – remember that health fades, and there are things you can do while you’re young that you can’t do in your old age. It’s quite painful, for instance, to have all the money to travel, but lack the health to do so.
A healthier, happier way to see wealth is to look beyond a dollar amount. Instead, view wealth as a means to live a life that you personally find fulfilling.
Price is definitely a factor. However, there’s another, equally important factor: most people are less interested in cheap, and are more interested in whether you can fix their problem.
Put yourself in the position of a customer. If your very important phone just broke, which would you prefer: a $50 repair service with a 50-50 shot of fixing it, or a $150 service that will fix it properly, with a warranty to boot?
If you keep thinking that “cheap” is the only way to sell your skills and services, you will constantly devalue yourself. It’s worse if you compromise on your work, to match the dollar value you charge. E.g.,if you can do great work for $150 an hour, but you charge $50 an hour to do subpar work, you will be known for subpar work.
As long as you’re honestly able to fix someone’s problem, don’t be afraid to charge more.
If your sole strategy is to budget, you don’t need much financial advice. 90 per cent of this strategy just involves saying “don’t buy that”.
Don’t buy a vacation package. Don’t buy a car. Don’t buy expensive coffee. See? It’s easy.
But you’ll often find that, even after all that crazy budgeting, you’re still somehow broke.
This is partly because, even to scrimp together an extra $200 a month, you need to make a surprising number of sacrifices.
No Grab rides even in the rain (save $15), no going to the movies (save $12), no eating out at the place you really like (save $20), no downloading a new game (save $60)…all that and we’re not even at $200 yet. And you need to go through this deprivation every month, if you need an extra $200 a month.
At some point, you will also realise that your budgeting has hit a limit. There will be no more costs left to cut. What happens if one day, you need an extra $1,500 a month to support a dependent? If $200 involves that degree of deprivation, consider what you need to lose from your life to reach $1,500.
This is why it’s unhealthy and disempowering, to think purely in terms of budgeting and saving. It’s definitely important to save and live within your means – but as a young person with many decades to go, you need to focus just as much attention on being able to earn more. This means not just saving and stuffing money in a bank, but upskilling for better wages, or learning to invest.
It’s often the opposite that’s true. People who don’t earn enough money to support themselves can become liabilities. In a crisis, they could end up depending on their family and friends.
Consider what it would feel like if, many decades from now, you still haven’t managed to improve your financial situation. In a crisis, would you need money from your retired parents to support you? Or would you be forced to stand by and watch loved ones struggle, because you lack the financial means to support them?
Trying to make more money isn’t just about materialistic aspirations. The holidays and new gadgets and a bigger house are all side benefits. Most people who successfully grow wealth started off with quite different motivations – such as wanting to better look after their family, or to fund projects and interests that would better their communities.
Don’t think of financial interests as being materialistic; think of them as ways to demonstrate care, or to further worthwhile causes.
This is a half-truth. It’s true that, if you have money, it’s easier to make more money. However, it doesn’t mean that you need to get crazy rich, before you start learning about investing and wealth management.
If you think about it, that sequence doesn’t make sense at all. The whole point of investing is to grow wealth – you get rich by investing, you don’t get rich first and then learn to invest (unless you’re a very rare case, like a lottery winner).
As a fresh graduate with an entry-level job, don’t handwave investing because you’re “too poor” for anything. It’s when your income and wealth are low, that you need to start investing more than ever.
Of course, this doesn’t mean investing in get-rich-quick schemes or gambling; your aim should be to develop a balanced, well-diversified portfolio. You can do this by either studying it yourself (joining the finance industry is a good way to get solid foundations), or by consulting qualified professionals.
At Exodus Capital, we steward both veterans and new entrants to the finance industry, in getting ahead with their careers. Do reach out to us for help, if you want career opportunities that can match your wider goals.